Press & Media Resources
Data, findings, and downloadable assets from Calccover's 2026 commercial insurance cost analysis.
About the Study
Title: Commercial Insurance Costs by State: The 5x Difference Small Business Owners Don't Know About
Published: September 23, 2026
Scope: Analysis of workers' compensation, general liability, and commercial auto insurance costs across all 50 US states. The study examines rate variation, identifies the most and least expensive states, and explores the regulatory factors that drive geographic pricing differences.
Key Findings
Headline Numbers
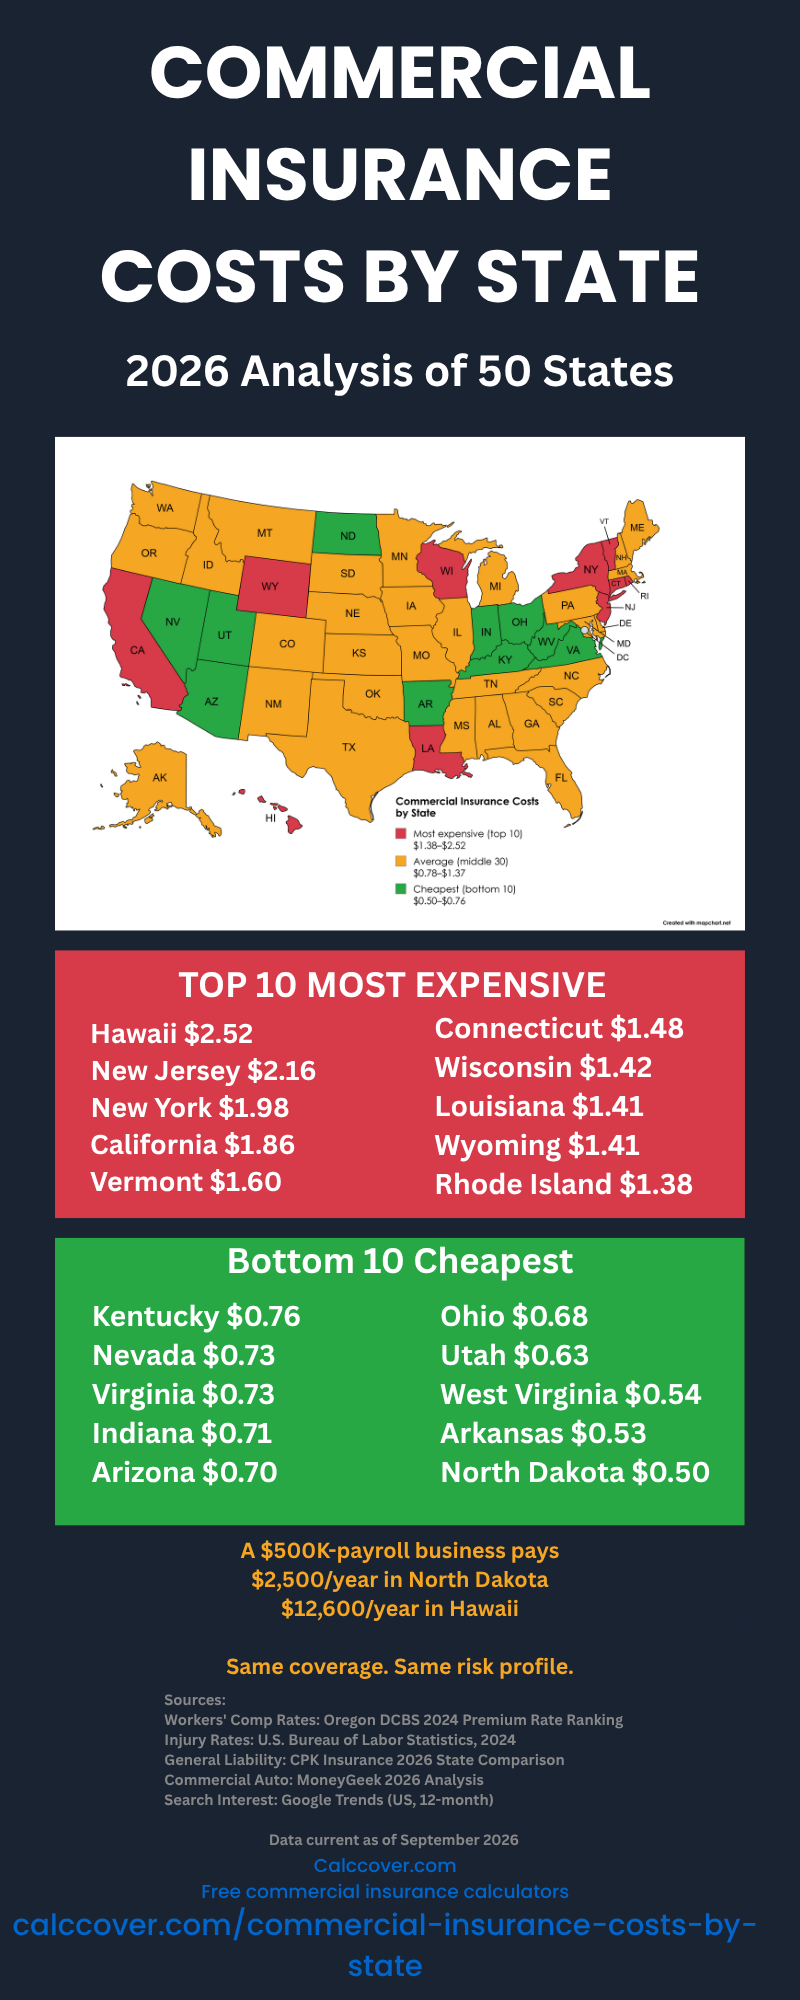
- Workers' comp rates vary 5x across US states — from $0.50 per $100 of payroll in North Dakota to $2.52 in Hawaii
- A small business with $500,000 in payroll pays $2,500/year in North Dakota and $12,600/year in Hawaii for identical workers' comp coverage — a $10,100 annual difference
- New York ranks in the top 5 most expensive states across all three major lines of commercial insurance (workers' comp #3, general liability #2, commercial auto #1)
- The Northeast pays 40–60% more than the Midwest or Mountain West for comparable coverage
- State-level injury rates do not predict state-level average premiums — Maine has the highest injury rate but a mid-tier workers' comp rate; North Dakota has an above-average injury rate and the cheapest rate in America
Downloadable Resources
Suggested Citation
Direct Quotes Available
On the cross-state variation:
"The same small business pays $2,500 or $12,600 per year for workers' comp depending entirely on which state they operate in. There's no other operating cost with that kind of geographic spread."
On the regional pattern:
"The Northeast consistently pays 40–60% more than the Midwest for identical commercial insurance coverage. The difference isn't worker safety — it's the regulatory and litigation environment."
On what business owners should do:
"State determines your base rate. Class code, experience modification, and payroll reporting determine what you pay on top of that. Both levers matter — they just operate at different levels."
Methodology Summary
Data sources include the Oregon Department of Consumer and Business Services (2024 Premium Rate Ranking), the U.S. Bureau of Labor Statistics (2024 Survey of Occupational Injuries and Illnesses), Insureon, CPK Insurance, MoneyGeek, and Google Trends. Rates reflect an average mix of low-to-moderate risk class codes for small businesses with 3–5 employees. Full methodology is available in the study.
Media Contact
For interview requests or additional data
Email: hello@calccover.com
We respond to press inquiries within 24 hours. Custom data cuts, regional breakdowns, and quote requests are available on request.
About Calccover
Calccover builds free commercial insurance calculators for small business owners, contractors, and fleet operators. Our tools estimate workers' comp, general liability, commercial auto, and other business insurance costs across all 50 states. All calculators are free and require no signup.